Boring Money Conference 2026: The FCA on Targeted Support, Simplified Advice and CCI
19 Oct, 2026

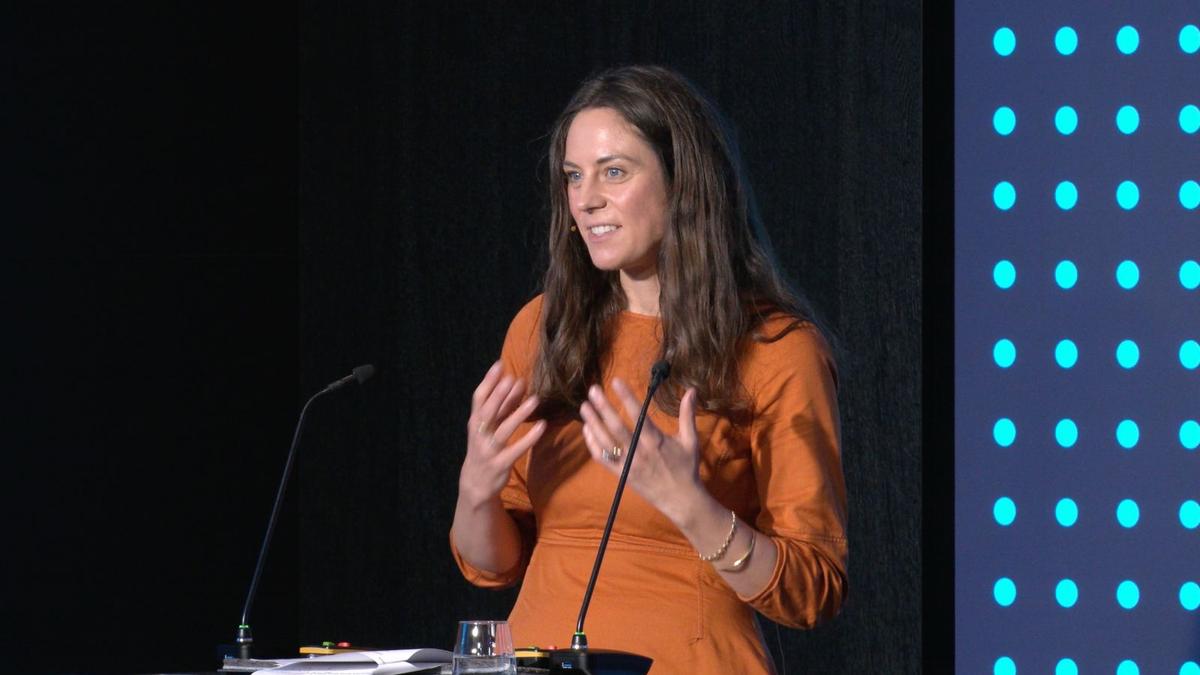
Kate Blatchford-Hick, Head of Consumer Investments Policy and Market Analysis at the FCA, speaking at the Boring Money Conference 2026: Investing Rewired
At the Boring Money Conference 2026, Investing Rewired: AI Meets the Consumer, Kate Blatchford-Hick, Head of Consumer Investments Policy and Market Analysis at the FCA, set out where the regulator has got to on what she called "the biggest set of changes to retail investment oversight in a generation".
Speaking in London on 7 October, she covered Targeted Support, Simplified Advice and the new Consumer Composite Investments (CCI) regime, before taking questions from Boring Money Founder and CEO Holly Mackay and the audience.
The FCA's ambition, she said, is for millions more people to find trusted support so they can understand their options and make informed decisions about saving and investing. The regulator estimates around 7 million UK adults currently hold more than £10,000 in cash savings.
She urged firms to go where their customers already are, including social media and AI tools: "If the only voices that they hear when they go through that is from unregulated firms, we've really missed an opportunity."
Preparing for CCI? The FCA has made it clear that firms have flexibility to create more consumer-centric product summaries. Our CCI Accelerator helps you test disclosures, evidence understanding, and demonstrate good outcomes with real UK investors.
Targeted Support
Targeted Support went live in April this year. It allows firms to offer ready-made suggestions to groups of consumers with similar characteristics and common needs, without the cost of a full holistic advice service.
Boring Money sizes the UK Advice Gap at 14.6 million people and estimates that Targeted Support could help lift 7.7 million of them out of the Gap. This is the largest single group, followed by coaching (2.9 million), Simplified Advice (720,000) and the traditional advice pipeline (1 million).
Kate described the early experience as "pretty encouraging". Ten firms are now authorised, and five of those now hold live propositions.
The first results suggest it can change behaviour:
Monzo found people who received an investment recommendation through its proposition were 33% more likely to open an investment account.
Royal London found consumers were 60% more likely to open a Stocks & Shares ISA after a Targeted Support recommendation than through an execution-only journey.
She drew three early lessons. There is no single model: some firms are building interactive app experiences, others are refining existing communications, and several are linking Targeted Support to their financial education offer. She also cited Chip building AI into its Targeted Support journey - we saw this demonstrated by Corinna Lamberti, Chip's Chief Product Officer, earlier in the day. Finally, consumer testing really matters, both so customers understand the limited scope of the service and so there are good "off-ramps" when a suggestion isn't right for them.
The FCA will keep monitoring outcomes and has committed to reviewing the regime's impact and effectiveness within two years.
Simplified Advice
The FCA wants to replace the "cliff edge" between advice and guidance with a spectrum of services. Kate pointed to people who have inherited money or hold cash to invest, and said the regulator is also testing where limited-scope advice could work in pensions journeys.
The "litmus test", she said, is that firms can make straightforward recommendations, gathering only enough information to show a recommendation is suitable. Consumers should get a short, clear explanation rather than a lengthy suitability document.
The ongoing advice rules are changing too. The FCA's proposal would move the standard from an annual suitability assessment to something more periodic, and Kate said firms are already thinking about how to reshape both the service and the price.
Kate was clear that neither Targeted Support nor Simplified Advice will replace comprehensive advice. They should give more people access to suitable help when full advice is unaffordable or unnecessary.
Appetite and AI
Boring Money's research shows the appetite is there, but the price point is not: 47% of investors and savers with £10,000 find Simplified Advice attractive, yet only 1 in 5 of them would pay £250 or more.
Earlier in the day, James McManus, Managing Director of J.P. Morgan Personal Investing, said Simplified Advice could be "phenomenal" for one-off needs such as inheriting a lump sum or managing a parent's retirement income, and expects fixed fees to be the likely model. Steven Levin, CEO of Quilter, saw "a big space" for Targeted Support and Simplified Advice, but warned AI is moving at "5 times the pace".
That pace is why Kate's message on AI was so direct. AI can help people learn, compare and ask better questions, she said, but "a large language model offering financial advice is not regulated financial advice". She pointed out that, concerningly, FCA research found 44% of 18–40-year-olds believe that it is.
Boring Money data shows why this is particularly important. 33% of DIY investors use AI for investment decisions, 22% of investors would be comfortable accepting AI recommendations, but just 4% would act on them.
Her advice to consumers was to use AI as a tool, not a substitute for judgment. For regulated firms, AI must be used responsibly, properly overseen and focused on good outcomes. The FCA has committed to publishing examples of good and poor practice in firms' use of AI later this year and will respond to the Mills Review on AI in due course.
CCI
The CCI regime aims to give consumers clear information at the right point in their journey. Kate said the case for reform was obvious, as only around 4% of existing KIIDs/KIDs were ever looked at.
The FCA has stopped prescribing templates. The key metrics (costs, returns and risk) stay consistent and comparable, but firms have much more freedom over how they present them. The transition began on 6 April 2026, and full implementation is 8 June 2027. Firms can use the new product summaries now, and the FCA encourages them to.
The regulator's baselining review found only 6% of current PRIIPs KIDs are written in plain English. It will repeat the exercise next year to track progress.
Kate outlined her test, asking simply whether the information helps people understand what they are buying, the risks involved and the decision they need to take. Manufacturers should produce concise, engaging documents, and distributors should think about layering and tailoring information through the journey.
She acknowledged this is a culture change and that removing templates takes away a "comfort blanket".
What the FCA wants to see is firms evidencing that they have genuinely asked what consumers need.
The FCA has also consulted on bringing MiFID and non-MiFID costs and charges rules into a single framework aligned with CCI, so consumers see costs presented the same way throughout. Feedback was broadly positive, with points raised on how costs are presented and how cash holdings are treated. Kate said the FCA must work at pace to give firms the final rules in good time for the CCI deadline.
The opportunity ahead
Holly's concern is that CCI, "such an amazing opportunity on paper", ends with "a KID document that's maybe about one page shorter". Boring Money's research shows what people want: when choosing a new fund, investors rank risk (43%) and costs to invest (42%) highest.
Q&A

Kate split it into the "what" and the "how". The strongest applications articulate a clear customer need, show how the journey meets it and delivers a better outcome, and explain how unsuitable customers will be identified. On the how: evidence that consumer testing shaped the proposition, good governance and controls, and a plan for monitoring outcomes, including trigger points and what the firm will do if results fall short.
Holly put it to Kate that the industry may arrive at June 2027 with KIDs that look little different, despite the 6% figure. Kate repeated that the FCA is not looking for perfection but wants firms to "have a go" and would be disappointed if that didn't happen. "We're not in the business here of trying to trip people up," she said, while noting that anything outrageously misleading would be a problem. She added that policy and supervision sit in the same directorate, which should help expectations carry through.
Asked by an audience member, Kate said the board is still reviewing its recommendations, and next steps will follow "fairly soon".
An audience member argued clients want a clear description of what a fund does, plus charges and risk, ideally on one page. Kate said success is not just consistency: metrics must be comparable, but documents will naturally vary by target market. They must also explain what a product is for and what outcome consumers might expect.
Richard Fox, Head of Public Policy at Schroders, asked whether the answer is good and poor practice guidance or thematic reviews. Kate said she is resisting publishing good and poor practice on CCI for now, without ruling it out, as she wants to see experimentation. The FCA will redo its baselining, which has two limbs: a readability score (the 6%) and an intelligibility score, which she described as "readability plus" and which was also very low.
Watch the full FCA keynote and Q&A
The FCA described these reforms as among the most significant changes to retail investment oversight in a generation. In this full session, Kate Blatchford-Hick discusses the progress of Targeted Support, upcoming Simplified Advice rules, the Consumer Composite Investments (CCI) regime and the FCA's approach to AI, before taking questions from Holly Mackay and the audience.